Paper "The Uncertainty in Extreme Risk Forecasts from Covariate-Augmented Volatility Models"
The paper "The Uncertainty in Extreme Risk Forecasts from Covariate-Augmented Volatility Models" by Dr. Yannick Hoga has been accepted by the peer reviewed International Journal of Forecasting. The publication can be found here....
Paper "On the parametric description of log-growth rates of cities’ sizes of four European countries and the USA"
The Paper "On the parametric description of log-growth rates of cities’ sizes of four European countries and the USA" by Dr. Till Massing, Dr. Miguel Puente-Ajovín und Dr. Arturo Ramos has been accepted by the peer reviewed...
Paper "Where does the tail begin? An approach based on scoring rules"
The paper "Where does the tail begin? An approach based on scoring rules" by Dr. Yannick Hoga has been accepted by the peer reviewed Journal Econometric Reviews. The publication can be found here.
Paper "Limit Theory for Forecasts of Extreme Distortion Risk Measures and Expectiles"
The paper "Limit Theory for Forecasts of Extreme Distortion Risk Measures and Expectiles" by Dr. Yannick Hoga has been accepted for the Journal of Financial Econometrics. The paper can be viewed here.
Paper "What is the best Lévy model for stock indices? A comparative study with a view to time consistency" published.
The paper "What is the best Lévy model for stock indices? A comparative study with a view to time consistency" by Dr. Till Massing has been accepted by the peer reviewed Journal Financial Markets and Portfolio Management. The...
Paper "On Combining Evidence from Heteroskedasticity Robust Panel Unit Root Tests in Pooled Regressions" published.
The Paper "On Combining Evidence from Heteroskedasticity Robust Panel Unit Root Tests in Pooled Regressions" by Prof. Dr. Christoph Hanck and Martin Arnold has been accepted by the peer reviewed Journal of Risk and Financial...
Paper "Local asymptotic normality for Student-Lévy processes under high-frequency sampling" published.
The paper "Local asymptotic normality for Student-Lévy processes under high-frequency sampling" by Dr. Till Massing has been accepted by the peer reviewed Journal Statistics.
Paper "E-Assessment Using Variable-Content Exercises in Mathematical Statistics" published.
The paper "E-Assessment Using Variable-Content Exercises in Mathematical Statistics" by Till Massing et. al. has been accepted by the peer reviewed Journal of Statistics Education.
Paper "Extending the Limits of Backtesting via the ‘Vanishing p’ Approach"
The paper "Extending the Limits of Backtesting via the ‘Vanishing p’ Approach" by Dr. Yannick Hoga has been accepted by the peer reviewed Journal of Time Series Analysis. The publication can be viewed here.
On 5th November 2018, Dr. Yannick Hoga received the economics award of Sparkasse Essen. He received the award, which is endowed with 5.000 €, for his dissertation "Detecting changes in the extremal behavior of time series"....
Publication of "Introduction to Econometrics with R"
The book Introduction to Econometrics with R by Christoph Hanck, Martin Arnold, Alexander Gerber and Martin Schmelzer has been published in the bookdown archive. The book is part of the project Reproducible Research in der...
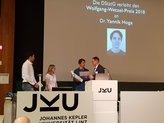
For his work in change point analysis, extreme value theory and financial econometrics, Dr. Yannick Hoga was awarded the Wolfgang Wetzel Award of the German Statistical Society (DStatG) at this years Statistical Week in Linz. The...

 Statistische Woche 2026
 Prof. Dr. Yannick Hoga appointed as Associate Editor des Journal of Financial Econometrics